
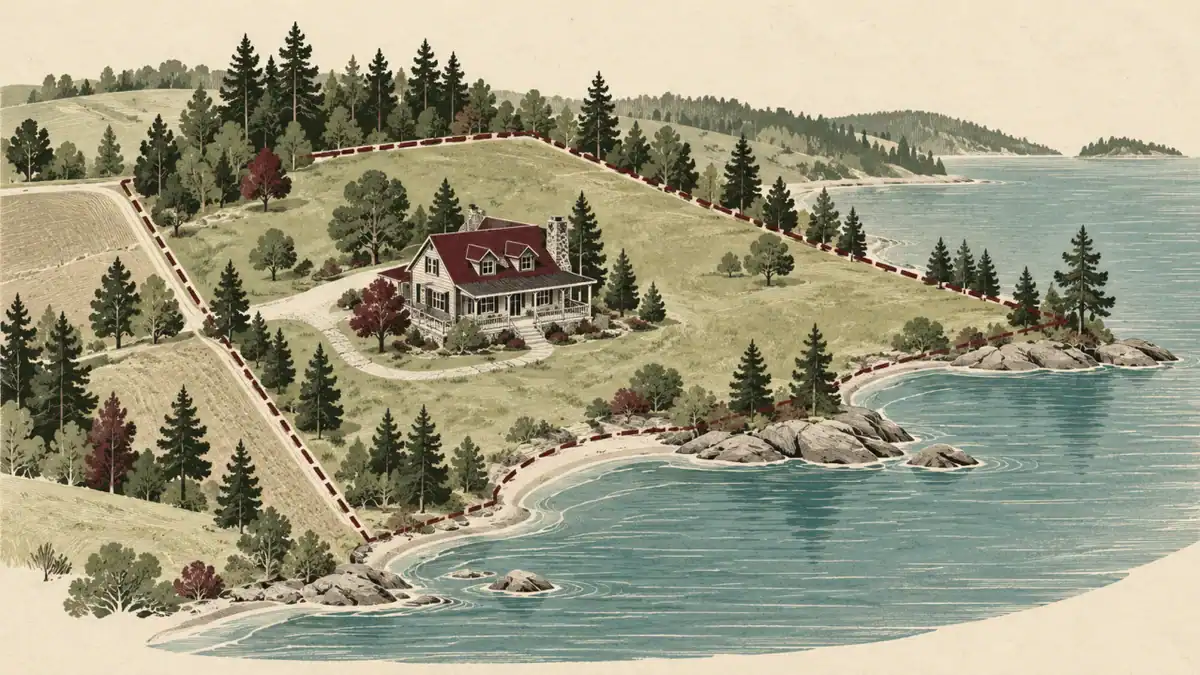
The property is valued as a whole
An acreage or waterfront appraisal does not begin with a fixed dollar amount for each acre, foot of shoreline, view or outbuilding. The appraiser first identifies the real estate being valued, the value date and the market in which buyers would compare the property.
The analysis considers how the residence, site, access, utilities, accessory improvements and water influence work together. A feature can contribute value, have little measurable effect or create a limitation. The conclusion must come from relevant market evidence rather than a rule of thumb or the feature's construction cost.
Start with the land and access facts
Acreage alone does not describe a site. Shape, topography, road access, easements, utilities, wells, septic systems, flood hazard, drainage and the portion that supports residential use may matter. Multiple parcels, leased land or shared roads should be identified early.
Provide a survey, legal description or parcel map when available. An appraisal is not a boundary survey, title opinion, environmental assessment or determination of development rights. Direct boundary, easement, water-right, zoning and environmental questions to the appropriate surveyor, attorney or government office.
Water influence requires more than a lake name
Waterfront and water-view properties can differ in shoreline ownership, legal access, dock rights, water depth, seasonal use, view range, erosion, flood exposure and distance from the water. A pond on the site, a lot bordering a lake and a distant water view are different property influences.
FEMA's Map Service Center is the official public source for federal flood-hazard maps, but a map does not answer every insurance, drainage or property-right question. Share flood documents, dock permits, association records and access agreements when they are relevant. The appraiser analyzes market reaction; other professionals address insurance, engineering and legal rights.
Comparable sales may come from a wider search
The best comparable sale is not always the closest or newest sale. Fannie Mae's guidance says appraisers should consider physical and legal characteristics such as site, finished area, style and condition, along with external factors such as a FEMA flood zone. Rural properties may require older sales or sales from competing market areas when nearby activity is limited.
If the search expands, the report should explain why those sales compete with the subject property and how important differences were considered. A sale with similar acreage but different access, utilities or water influence may be less useful than a more distant sale that appeals to the same buyers.
Adjustments must reflect the market
There is no universal per-acre, per-square-foot or waterfront adjustment. Fannie Mae instructs appraisers to base adjustments on market reaction and warns against unsupported rules of thumb. The same principle applies in private work: the analysis should show how buyers respond to a meaningful difference whenever the available evidence permits.
Outbuildings also require context. A small shed, detached shop, horse facility and agricultural building serve different users. Condition, utility and whether the property remains residential in character affect how the improvement is described and analyzed.
Prepare a concise property record
A short, organized record helps Red Oak identify the property and research required before quoting the work.
- Street address, parcel numbers, acreage and number of parcels
- Survey, legal description, easements and shared-access documents
- Well, septic, utility and private-road information
- Outbuilding uses, approximate sizes, condition and available permits
- Water frontage, legal access, dock or association records and known flood documents
- The decision, value date, people relying on the report and deadline
Confirm service-area and property fit
Red Oak lists acreage and waterfront among its residential appraisal qualifications, but every property still requires review. Coverage is limited to the firm's published Missouri service area; a lake name, mailing city or rural location does not establish coverage by itself. Send the exact address and parcel details first.
Jacob Coffman, Missouri Licensed Residential Appraiser, will review the location, property type, intended use and available evidence before Red Oak confirms whether it can accept the work and quote the fee and timing.
Helpful sources
- Appraisal Institute — How consumers interact with appraisers
- Fannie Mae — Comparable sales
- Fannie Mae — Adjustments to comparable sales
- FEMA — Flood Map Service Center
Explore the related appraisal service · Read the appraisal FAQ · Request a private appraisal quote